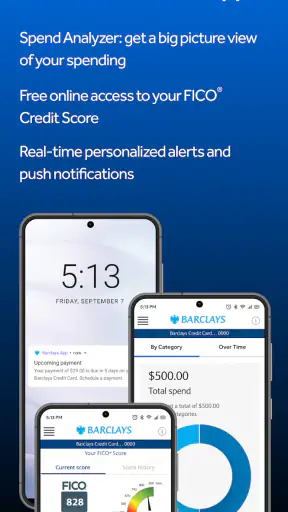
Managing a credit card from a phone sounds simple until a payment is due, a purchase needs checking, or an unexpected charge appears while you are away from your computer. I reviewed Barclays US as a mobile finance app from Barclays US, focusing less on its short promise of being safe, convenient, and rewarding and more on how it fits into an ordinary banking routine. My overall impression is that it works best as a practical control panel for Barclays customers, especially people who want to check activity and deal with routine account tasks without opening a desktop browser.
The app is free and aimed at everyone, which makes the entry point uncomplicated. It has reached more than one million installs and holds a 4.6 average from around sixty thousand ratings, with roughly seven thousand reviews. Those figures suggest that it is not a niche companion app used only by a small group of cardholders. Still, popularity does not automatically make it the right finance tool for every person. The important question is whether your day-to-day money workflow begins with a Barclays US account or card.
From a pending purchase to a completed payment
Starting with the situation that actually matters
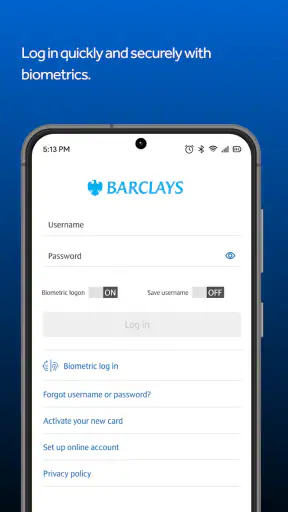
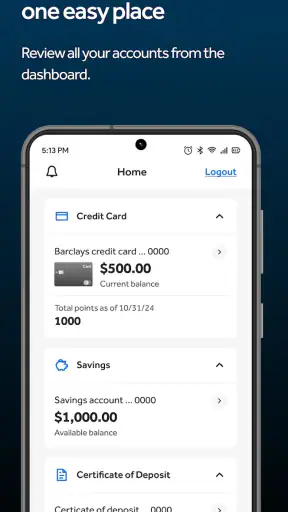
Imagine I am leaving a supermarket and want to confirm that the transaction has appeared on my account. I do not want to wait until I get home, search for a password on a laptop, or rely on a paper statement. I open the app, sign in, and use the account view as the first checkpoint. That is the kind of starting condition where this app makes sense: I already have a Barclays relationship, I need current account information, and I want to complete a small task quickly.
The same starting point applies when I am preparing a payment. Before sending money, I want to know which account I am using, what activity has recently posted, and whether a payment is already in progress. A finance app should reduce uncertainty rather than merely display a polished home screen. In my experience, the value here comes from having account access and action steps in one place, not from replacing every financial tool I use.
New users should begin by checking that their device meets the app’s minimum operating-system requirement. The current version is 8.7.2 and requires operating system 12 or later. That is an easy detail to overlook when an app appears in a search result, but it can decide whether installation is possible. I would also make sure I am using the official Barclays US app and not an unrelated finance application with a similar-looking name.
Checking the account before taking action
My first habit would be to review recent activity before making a payment. This is more useful than immediately tapping the most prominent button because it gives context: a purchase may still be pending, a payment may already have reduced what is owed, or a transaction may look unfamiliar. That short pause can prevent duplicate payments and helps separate a genuine problem from a normal delay in transaction processing.
For a household budget, I would use the app as a verification layer rather than as my only record. For example, after buying groceries, I could check whether the charge is visible, then compare it with my own spending note. If the amount is different from what I expected, I would investigate before assuming the app is wrong. Mobile account views are excellent for current awareness, but I would not treat them as a complete replacement for a longer-term budgeting system.
One useful workflow is to check activity at two different moments: shortly after a purchase and again before the payment deadline. The first check helps me notice something unusual while the memory is fresh. The second check helps me avoid acting on an incomplete picture. This is a small discipline, but it is more valuable than repeatedly refreshing the screen without a purpose.
Moving from review to payment
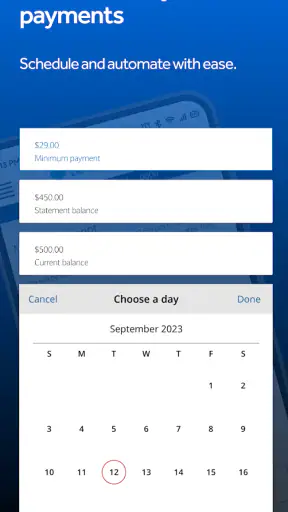
Once I understand the current account position, I can move to the payment task. The important handoff is from information to commitment. Looking at a balance is reversible; submitting a payment is not something I would rush. I would read the amount carefully, confirm the selected account details, and review the final screen before submitting.
This is where a mobile interface has a real advantage over a browser for some users. I can deal with a payment while commuting, during a lunch break, or immediately after noticing that a due date is approaching. The trade-off is that a small phone screen gives me less room to compare several accounts or documents at once. If I am handling an unusual amount or trying to reconcile several months of activity, I would prefer a larger screen and a calmer setting.
I would also avoid making a payment over an unreliable connection. A frozen screen or delayed confirmation can create doubt about whether the action went through. Rather than tapping repeatedly, I would wait, reopen the account activity, and look for a clear status. That approach prevents one of the most common mobile-finance mistakes: submitting the same action more than once because the first result was not immediately visible.
The handoff between phone, bank, and personal records
The app is only one part of the process. The phone sends my request, Barclays US processes it, and my own budget or calendar remains responsible for the wider plan. Thinking in those terms helps me use the app realistically. It can be the place where I initiate or verify an account task, but it cannot decide whether the payment fits my monthly cash flow.
After completing a payment, I would save the confirmation in whatever personal system I already use, such as a calendar note or household spreadsheet. I would not copy every transaction manually unless I needed that level of detail. A better compromise is to record the payment date, amount, and purpose, then use the app later to verify the account activity. This creates a simple audit trail without turning a routine task into clerical work.
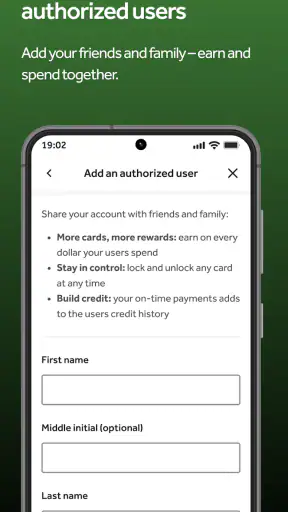
That handoff also matters when another person helps manage household finances. I would be cautious about sharing login credentials or leaving the phone unlocked just to make a joint task easier. If a partner needs information, I would share the relevant amount or status through an appropriate channel rather than treating the app as a shared notebook. Convenience should not erase basic account privacy.
What the completed workflow feels like
The successful outcome is not merely seeing a balance. It is knowing what happened, completing the intended action once, and being able to return to normal life without uncertainty. In the supermarket example, that means checking the purchase, recognizing whether it is pending or posted, and keeping the result in context with my budget. In the payment example, it means reviewing the account, submitting deliberately, and confirming the resulting status.
That makes Barclays US most useful for short, repeatable jobs. I can imagine using it before a purchase, after a purchase, and whenever a payment needs attention. The app’s strength is the reduction of distance between noticing a financial task and dealing with it. I do not need to wait for a statement cycle or sit at a desktop for every small decision.
It is also a reasonable choice for users who prefer a focused banking experience instead of a broad personal-finance dashboard. The app’s role is closely tied to Barclays US account access. That focus can feel cleaner than an all-in-one budgeting service filled with accounts, charts, and categories I may not need. On the other hand, someone looking for detailed spending analysis across several institutions may find a dedicated budgeting app more suitable.
Where the flow becomes less comfortable
The first limitation is scope. If I do not use Barclays US, the app has little reason to be part of my daily routine. It is not a general-purpose wallet or a neutral comparison tool for every bank. Even for a Barclays customer, it may not replace the broader financial picture I keep elsewhere, especially if I have accounts with multiple providers.
The second limitation is the phone format itself. A mobile app is convenient for checking a transaction or handling a routine payment, but it is not always the best environment for complicated financial review. Comparing many entries, reading long account information, or resolving an unfamiliar issue can be tiring on a small display. When the task becomes investigative rather than routine, I would move to a larger screen or contact the bank through the appropriate support route.
There is also a psychological risk in making payments too easy. Because the app is available whenever I have my phone, I might be tempted to act quickly without checking the amount or timing. My rule would be simple: use the app for speed, but keep the final review slow. That single habit matters more than any interface shortcut.
Users should also plan for situations in which a transaction does not appear immediately or a confirmation is delayed. I would not assume that a missing item means the purchase failed, nor would I assume that a displayed item is fully settled merely because it is visible. When timing matters, I would check the status carefully and allow room for processing rather than waiting until the last possible moment.
Who should use it, and who should choose something else?
I would recommend this app to Barclays US customers who regularly manage their accounts from a phone, want quick access to transaction activity, and prefer handling routine payment tasks without a desktop browser. It also suits people who want a direct relationship with their bank rather than routing every action through a third-party finance service.
I would be more cautious about recommending it to someone whose main goal is a complete household budget across several banks, investments, loans, and cash accounts. A dedicated budgeting application may offer a better overview for that use case. Likewise, if I rarely use mobile banking or prefer reviewing finances on a computer, the app’s convenience may not justify changing my established routine.
It is worth remembering that the app is free, but “free” does not mean it removes every responsibility from the user. I still need to protect access to my device, verify payment details, monitor activity, and maintain a sensible record of important transactions. The app can make those jobs easier; it cannot perform the judgment behind them.
My final take after following the full process
Barclays US succeeds when I treat it as a practical bridge between a financial event and a clear next step. A purchase happens, I check it. A payment needs attention, I review the account and submit it carefully. A result is expected, I return to the activity view and confirm it. That complete workflow is more convincing than the app’s short marketing summary because it shows where the product earns its place on my phone.
My honest recommendation is therefore specific: Barclays customers who want dependable mobile access should give it a try, while users seeking broad financial planning should pair it with another tool or choose a service built for that wider job. The app has a strong 4.6 average across around sixty thousand ratings, and its established presence supports the idea that it is a mature option rather than an experimental download. Even so, its best quality is not the number attached to it. It is the ability to turn ordinary account maintenance into a short, understandable routine.
Before relying on it for an important deadline, I would install it on a compatible device, sign in calmly, inspect the account layout, and complete a low-risk check first. Once I know where activity and payment confirmation appear, the app becomes much easier to trust in real situations. My main advice is to use its speed for routine tasks, but keep your own verification step for every consequential payment.


